FOR RENTExpat
Rs65K/mo
The Finance Bill 2026 is now law: non-citizen duty back to 5%, a new 10% seller duty on some State land sales, and bigger first-time buyer relief.
The Finance Bill 2026 is no longer a proposal: it received presidential assent on 12 August 2026 and was published in the Government Gazette on 13 August 2026, becoming the Finance Act 2026. For property, the headline change is that the 10% registration duty and 10% land transfer tax introduced for non-citizens last year have been repealed, restoring the standard 5% rates, while a new 10% duty now falls on sellers in certain State land transactions. First-time buyer relief has also increased.
This article sets out what actually changed in law on 13 August 2026, what was only announced, and what buyers, owners, landlords and sellers should check before signing anything.
The most significant property measure in the Finance Act 2026 is the repeal of last year's duty increase. The Finance Act 2025 had raised registration duty, paid by the buyer, and land transfer tax, paid by the seller, from 5% to 10% for non-citizens purchasing residential property under the EDB schemes (PDS, Smart City, RES, Invest Hotel) and the G+2 apartment route, for deeds registered from 1 July 2026. The Finance Act 2026 repeals those increases. The standard 5% registration duty and 5% land transfer tax now apply again. Some early summaries of the Bill suggested the 10% registration duty would remain in place, but the enacted text repeals it in full.
Anyone who registered a deed between 1 July 2026 and 12 August 2026, a window the repeal does not expressly address, should ask their notary how that specific transaction is treated. This is a case-by-case question that cannot be answered in general terms.
A new duty has also been introduced. Where residential property on State land or Pas Géométriques is sold to a non-citizen under the G+2 route, the seller must now pay an additional 10% duty, on top of the normal duty, under section 3(3)(c)(v) of the Non-Citizens (Property Restriction) Act. This additional duty does not apply where a presale agreement, meaning a VEFA reservation contract or a promesse de vente, was signed before 19 June 2026 and was drawn up and signed before a notary. It has no effect on sales to Mauritian citizens.
Separately, the Budget announced that no new State land or Pas Géométriques leases would be approved for G+2 apartments sold to foreigners, with existing approved leases and existing owners excluded from the restriction. This is an announcement only. It is not contained in the Finance Act 2026 or the Economic and Financial Measures (Miscellaneous Provisions) Act 2026, and is not yet law.
What has not changed: the USD 375,000 property-linked residence permit, the core PDS, Smart City, IRS and RES scheme rules, campement tax, and VAT treatment of residential property are all unaffected by this year's Act, apart from the duty repeal described above. Buyers working through the purchase process for the first time may find it useful to read our guide to buying property in Mauritius and our overview of the legal process for buying property.
Mauritian first-time buyers benefit from increased registration duty relief under the Finance Act 2026. The maximum relief and the value threshold it corresponds to have both risen for bare land and for a house or apartment.
| Purchase type | Previous maximum relief | Previous threshold | New maximum relief | New threshold |
|---|---|---|---|---|
| Bare land | Rs 125,000 | First Rs 2.5 million | Rs 150,000 | First Rs 3 million |
| House or apartment | Rs 250,000 | First Rs 5 million | Rs 300,000 | First Rs 6 million |
In addition, owning agricultural land no longer disqualifies a buyer from claiming first-time buyer relief. The Registrar-General retains the power to claw back the relief where a buyer's declaration supporting the claim was false, so accuracy in the declaration remains important.
Several measures affect owners who rent out or sell property. From income year 2026-27, the Central Electricity Board and the Central Water Authority must report to the Mauritius Revenue Authority, by 15 August each year, every customer billed more than Rs 100,000 in an income year, together with the property address. Landlords should expect the MRA to compare this utility data against declared rental income, so accurate rental declarations matter more than before. Rental income itself continues to be taxed within the normal personal income tax bands, with no rental-specific change introduced this year.
Owners who let property as short-term tourist accommodation should note that a temporary tourist accommodation certificate is now available, valid for up to 90 days while an operator completes compliance, with the Tourism Authority required to decide on applications within 21 days.
For sellers involved in a dispute over a land duty claim, whether by objection or appeal, the amount payable upfront has been set at 5% of the claim or Rs 5 million, whichever is lower. Those ordering property searches should also budget for higher Registrar-General fees, which rise from Rs 200 to Rs 300 per day and from Rs 2,000 to Rs 5,000 per month.
On morcellement (subdivision) matters, the requirements for an Association Foncière and for a green forest have been removed, including for applications already pending, though the requirement for 2% green space on developments of more than 20 lots remains in place. Transfers by the NHDC or the NSLD to a syndicat de copropriétaires are now exempt from registration duty, land transfer tax and the tax on transfer of State land leasehold rights. Readers wanting a fuller picture of duty and tax obligations when selling or transferring property may find our guide to the legal and tax implications of buying property in Mauritius useful background, alongside advice from a notary.
Personal income tax bands change from the income year starting 1 July 2026. The system remains progressive, meaning only the portion of income within each band is taxed at that band's rate.
| Chargeable income band | Rate |
|---|---|
| First Rs 500,000 | 0% |
| Next Rs 500,000 | 10% |
| Next Rs 11 million | 20% |
| Above Rs 12 million | 35% |
The individual Fair Share Contribution now applies only to income year 2025-26. The tax-exempt limit for qualifying lump sums, such as a pension, retiring allowance or severance payment, rises from Rs 3 million to Rs 3.5 million. Mauritius continues to levy no capital gains tax and no inheritance tax.
A Golden Visa holder who invests at least USD 1 million within 12 months in a business activity can now obtain permanent residence. Buying residential property under the EDB schemes does not count towards this investment requirement. Golden Visa holders receive the same remittance-basis tax treatment as Premium Visa holders. The specific threshold for the visa itself is left to guidelines rather than set out in the Act. Separately, a PDS or Smart City purchase of USD 375,000 or more continues to give the buyer and family a residence permit for as long as the property is held. This is a residence permit, not permanent residency.
Occupation Permit rules have also changed. For the Investor category, the minimum initial investment is now USD 100,000, with the previous USD 50,000 option removed; renewal requires turnover of Rs 5 million from year 3 and Rs 8 million from year 5. For the Professional category, the minimum monthly basic salary is Rs 50,000. For the Self-employed category, the minimum investment is USD 50,000, with renewal requiring turnover of Rs 2 million from year 3 and Rs 3 million from year 5. The Family Occupation Permit has been abolished.
A number of further changes were introduced alongside the property and tax measures. The period for claiming input VAT credits is reduced from 36 months to 24 months. A tax deduction at source now applies at 1% on certain company payments to ICT service providers, and at 5% on payments for advertising, promotion, endorsement or marketing carried out through social media or other digital channels. A new insurance premium tax is also introduced; check the Act or your insurer for its rate and start date. The Act also establishes an AI City Scheme and a Private Wealth Management licence, changes maternity and paternity leave and introduces menstrual leave, and tightens rules on promoting virtual assets.
Anyone currently transacting should treat the gazettal date of 13 August 2026 as the reference point for the repealed and new property duties. In practice this means:
Browse current listings on PropertyFinder Mauritius, or contact us if you would like to discuss a specific transaction.
Yes. It received assent on 12 August 2026 and was published in the Government Gazette on 13 August 2026, becoming the Finance Act 2026, alongside the Economic and Financial Measures (Miscellaneous Provisions) Act 2026.
No. The Finance Act 2025 had raised both to 10% for deeds registered from 1 July 2026. The Finance Act 2026 repeals that increase, so the standard 5% registration duty and 5% land transfer tax apply again.
The Finance Act 2026 does not expressly address deeds registered in that period, so confirm how your transaction is treated directly with your notary.
Yes. Sellers of residential property on State land or Pas Géométriques transferred to a non-citizen under the G+2 route must now pay an additional 10% duty, unless a qualifying presale agreement was signed before 19 June 2026 before a notary. This does not affect sales to Mauritian citizens.
Not yet. A restriction on new State land and Pas Géométriques leases for G+2 apartments sold to foreigners was announced in the Budget, with existing approved leases and owners excluded, but this has not been enacted in either the Finance Act 2026 or the Economic and Financial Measures (Miscellaneous Provisions) Act 2026.
No. A PDS or Smart City purchase of USD 375,000 or more continues to entitle the buyer and family to a residence permit for as long as the property is held. This is unchanged by the Finance Act 2026 and remains a residence permit rather than permanent residency.
Hand-picked
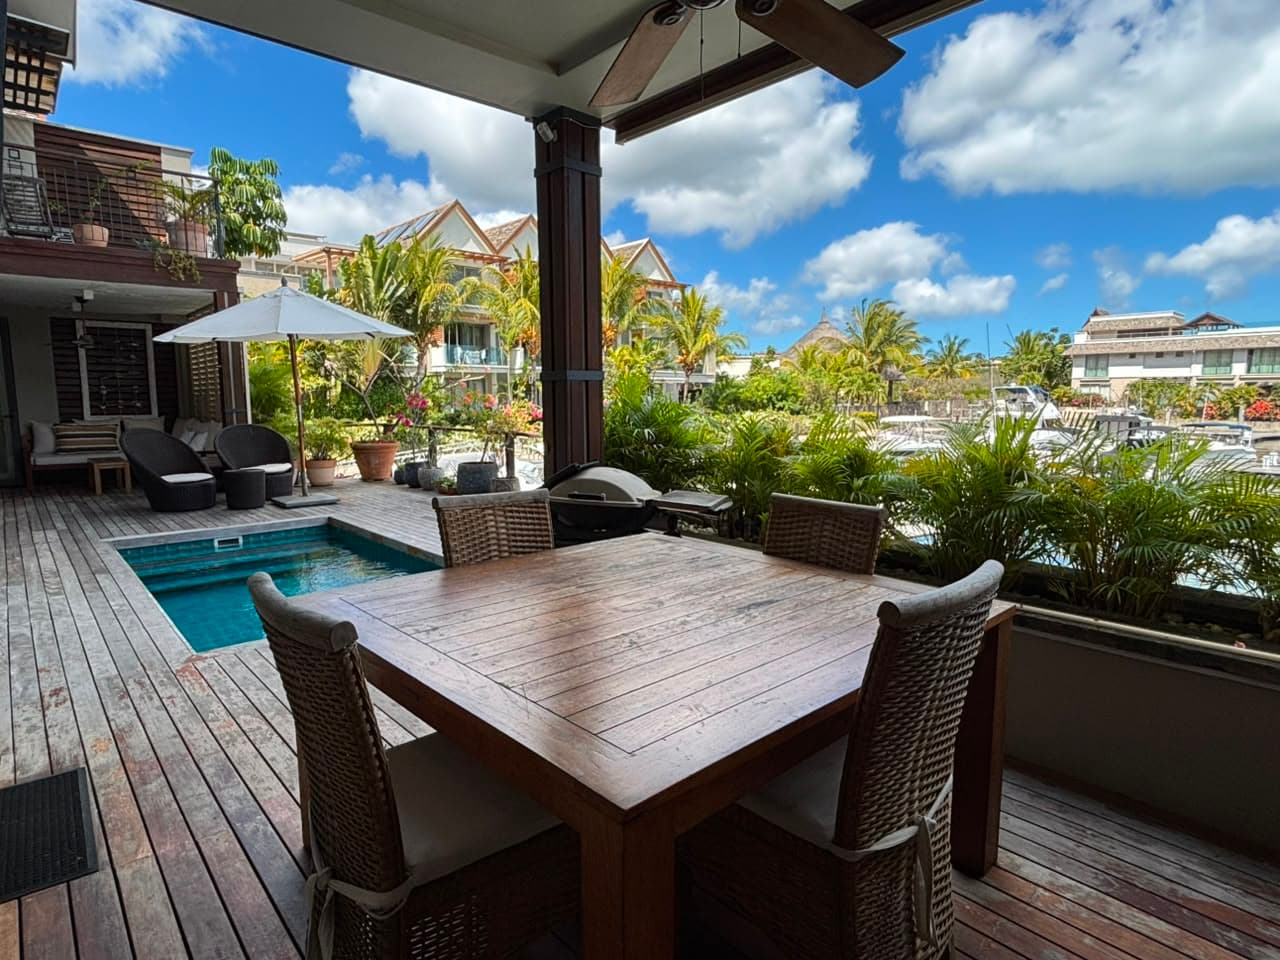
Riviere Noire · West

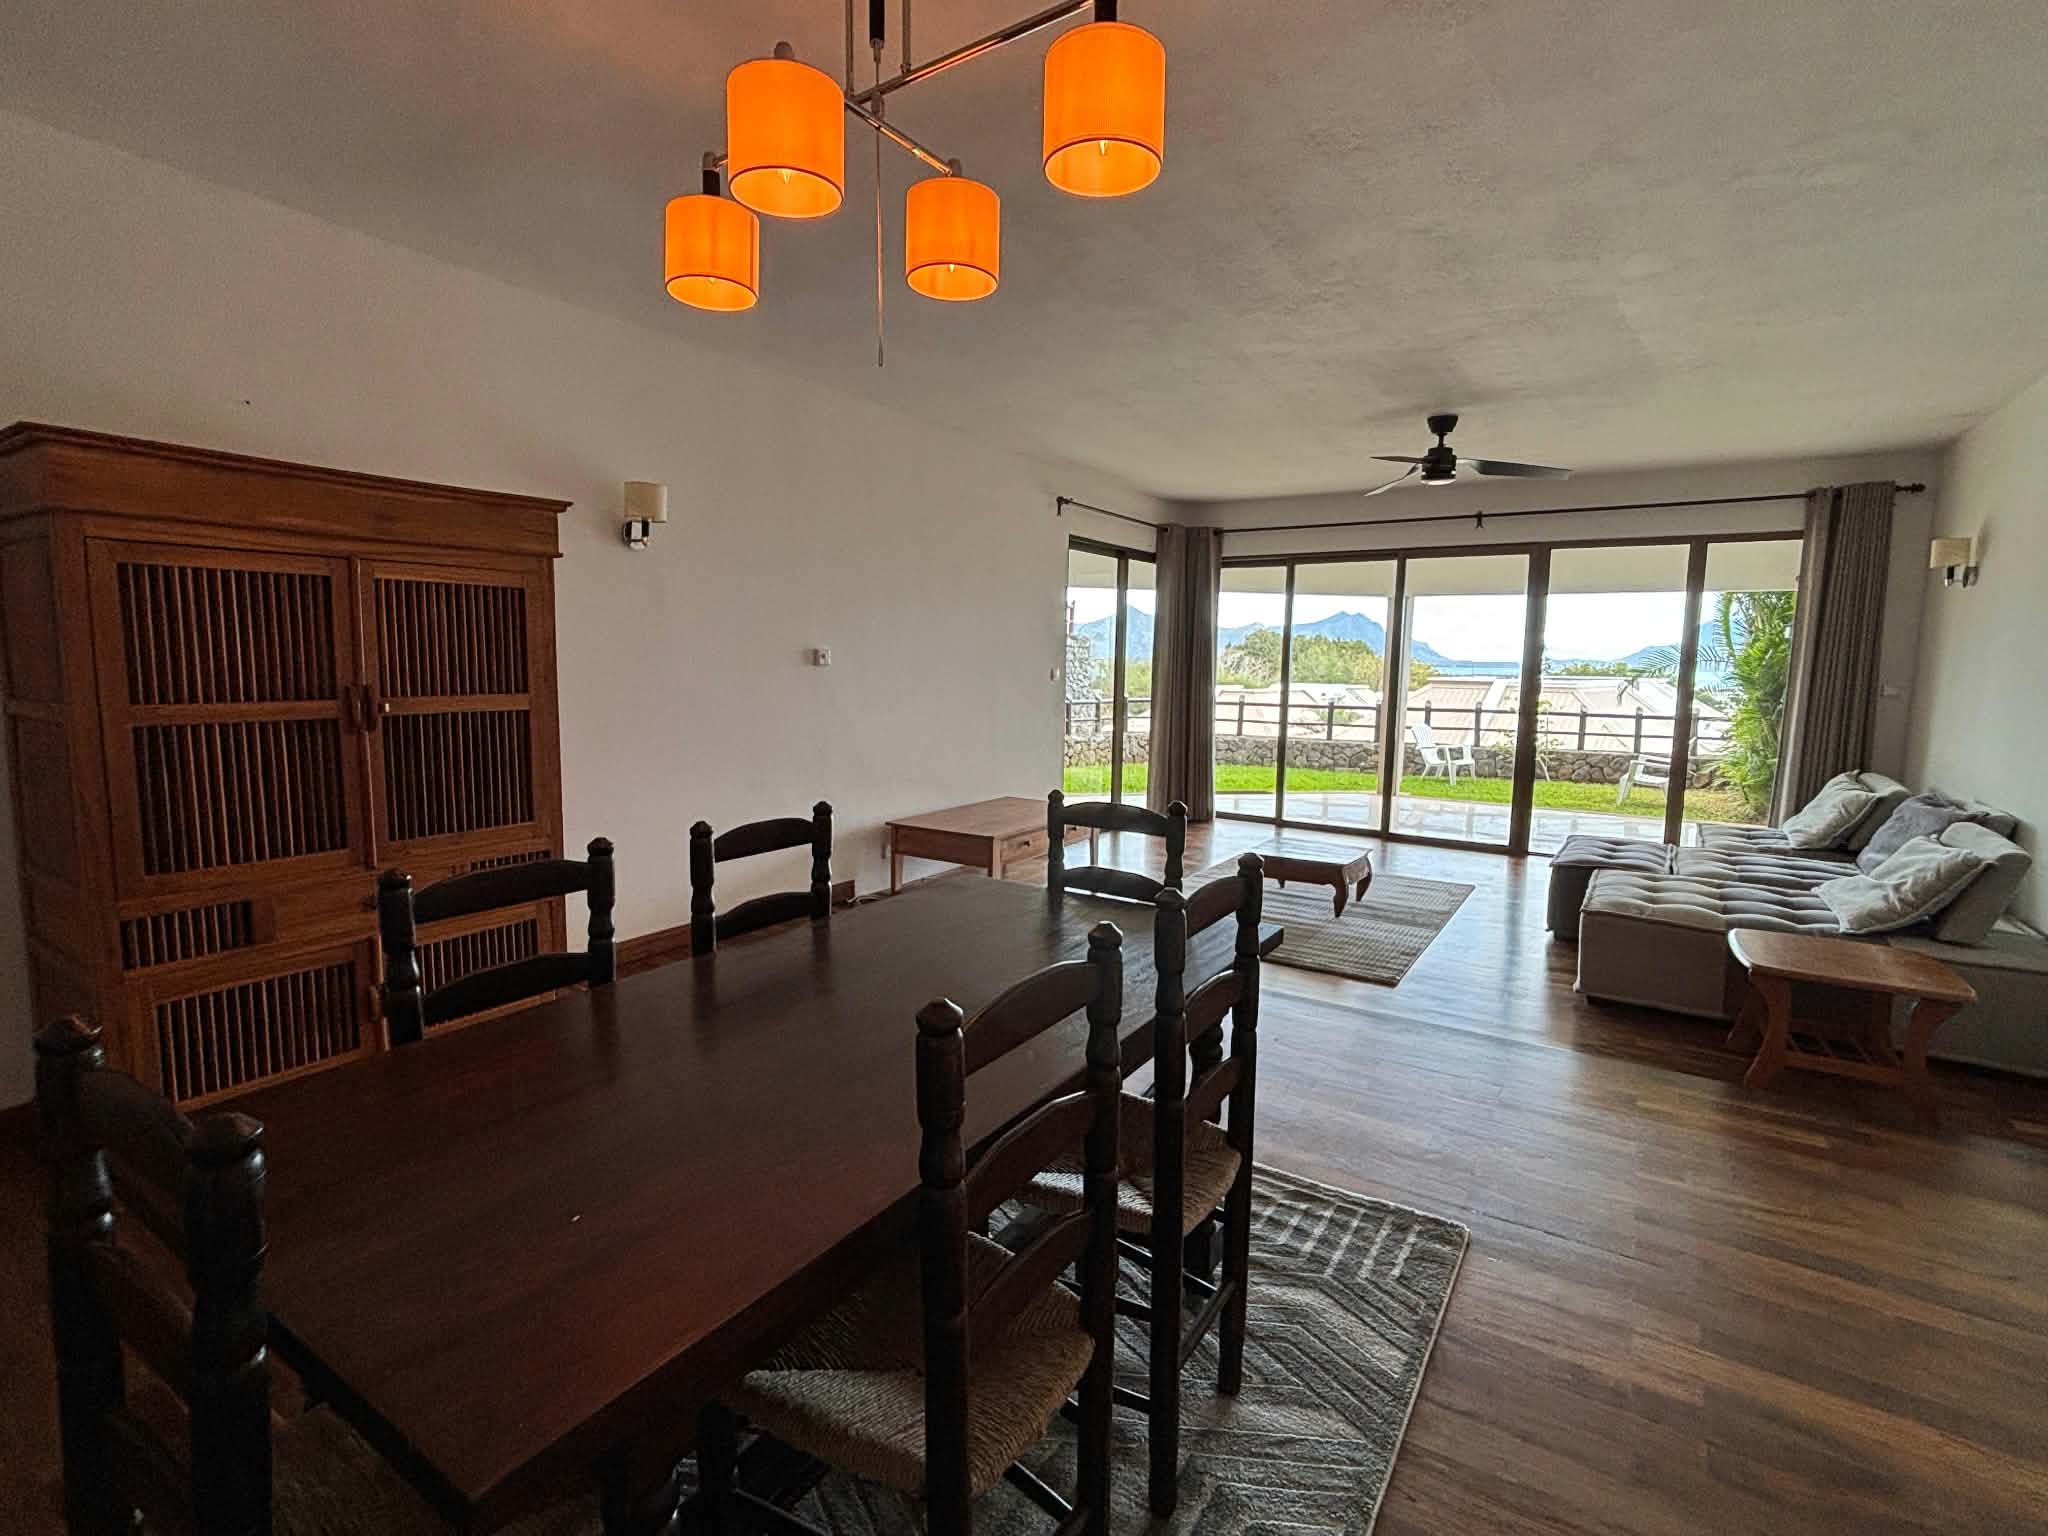
Tamarin · West

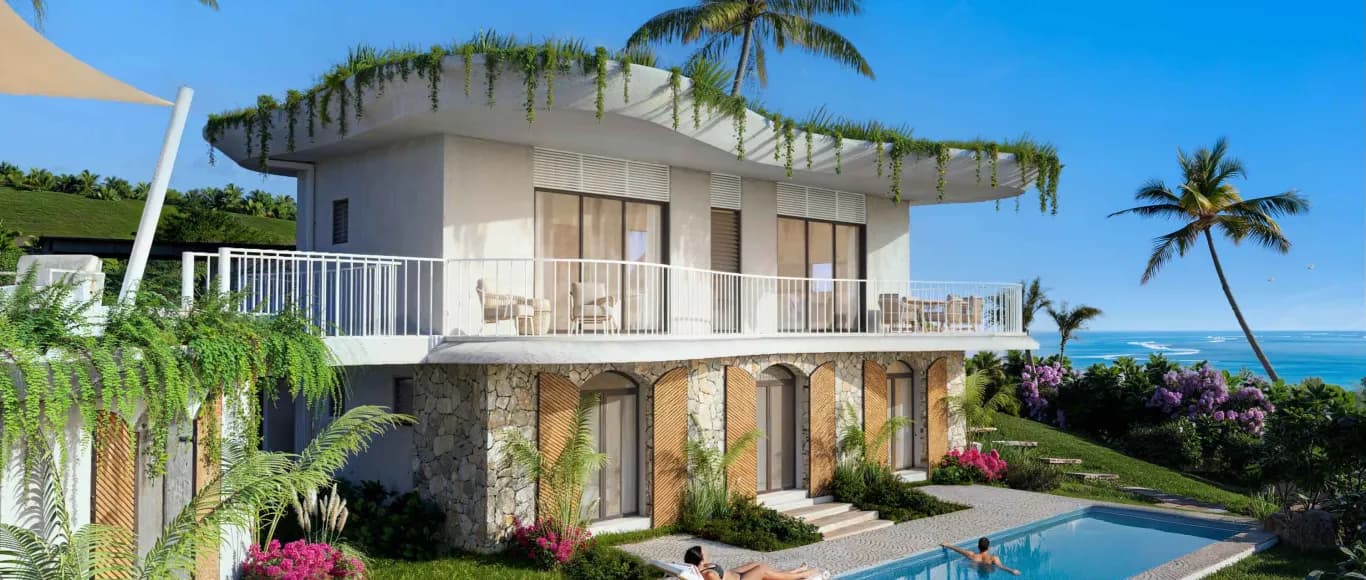
Baie du Cap · South
Tamarin · West
Beau Champ · East
Baie du Cap · South
Explore by region
Explore the site
Market updates, buying guidance and the best new listings, straight to your inbox.
Mauritius Real Estate · 21 Oct 2026
Discover Beaubassin, Mauritius: location, lifestyle, amenities, and property opportunities for buyers and renters in this quiet east-coast…
Mauritius Real Estate · 20 Oct 2026
Browse holiday apartments in Mauritius for rent or sale. Discover top areas, what to budget, and how the buying process works for foreign nationals.
Mauritius Real Estate · 20 Oct 2026
Understand Mauritius land size, local measurement units like arpents and toises, and what they mean for buying residential or farm land in Mauritius.
Mauritius Real Estate · 20 Oct 2026
What is the Smart City Scheme in Mauritius, which projects exist, and how do foreign buyers qualify for residency? Clear answers and costs in one…
Mauritius Real Estate · 20 Oct 2026
Step-by-step guide to the legal process of buying property in Mauritius: eligibility, preliminary agreement, notary deed, duties and title…
Mauritius Real Estate · 20 Oct 2026
Explore property in Flacq District, Mauritius: area guide, neighbourhoods, price ranges, apartments for rent, houses for sale, and buying tips for…
Browse our current listings or speak to an agent.